
Available now
Turnkey
$734
per week
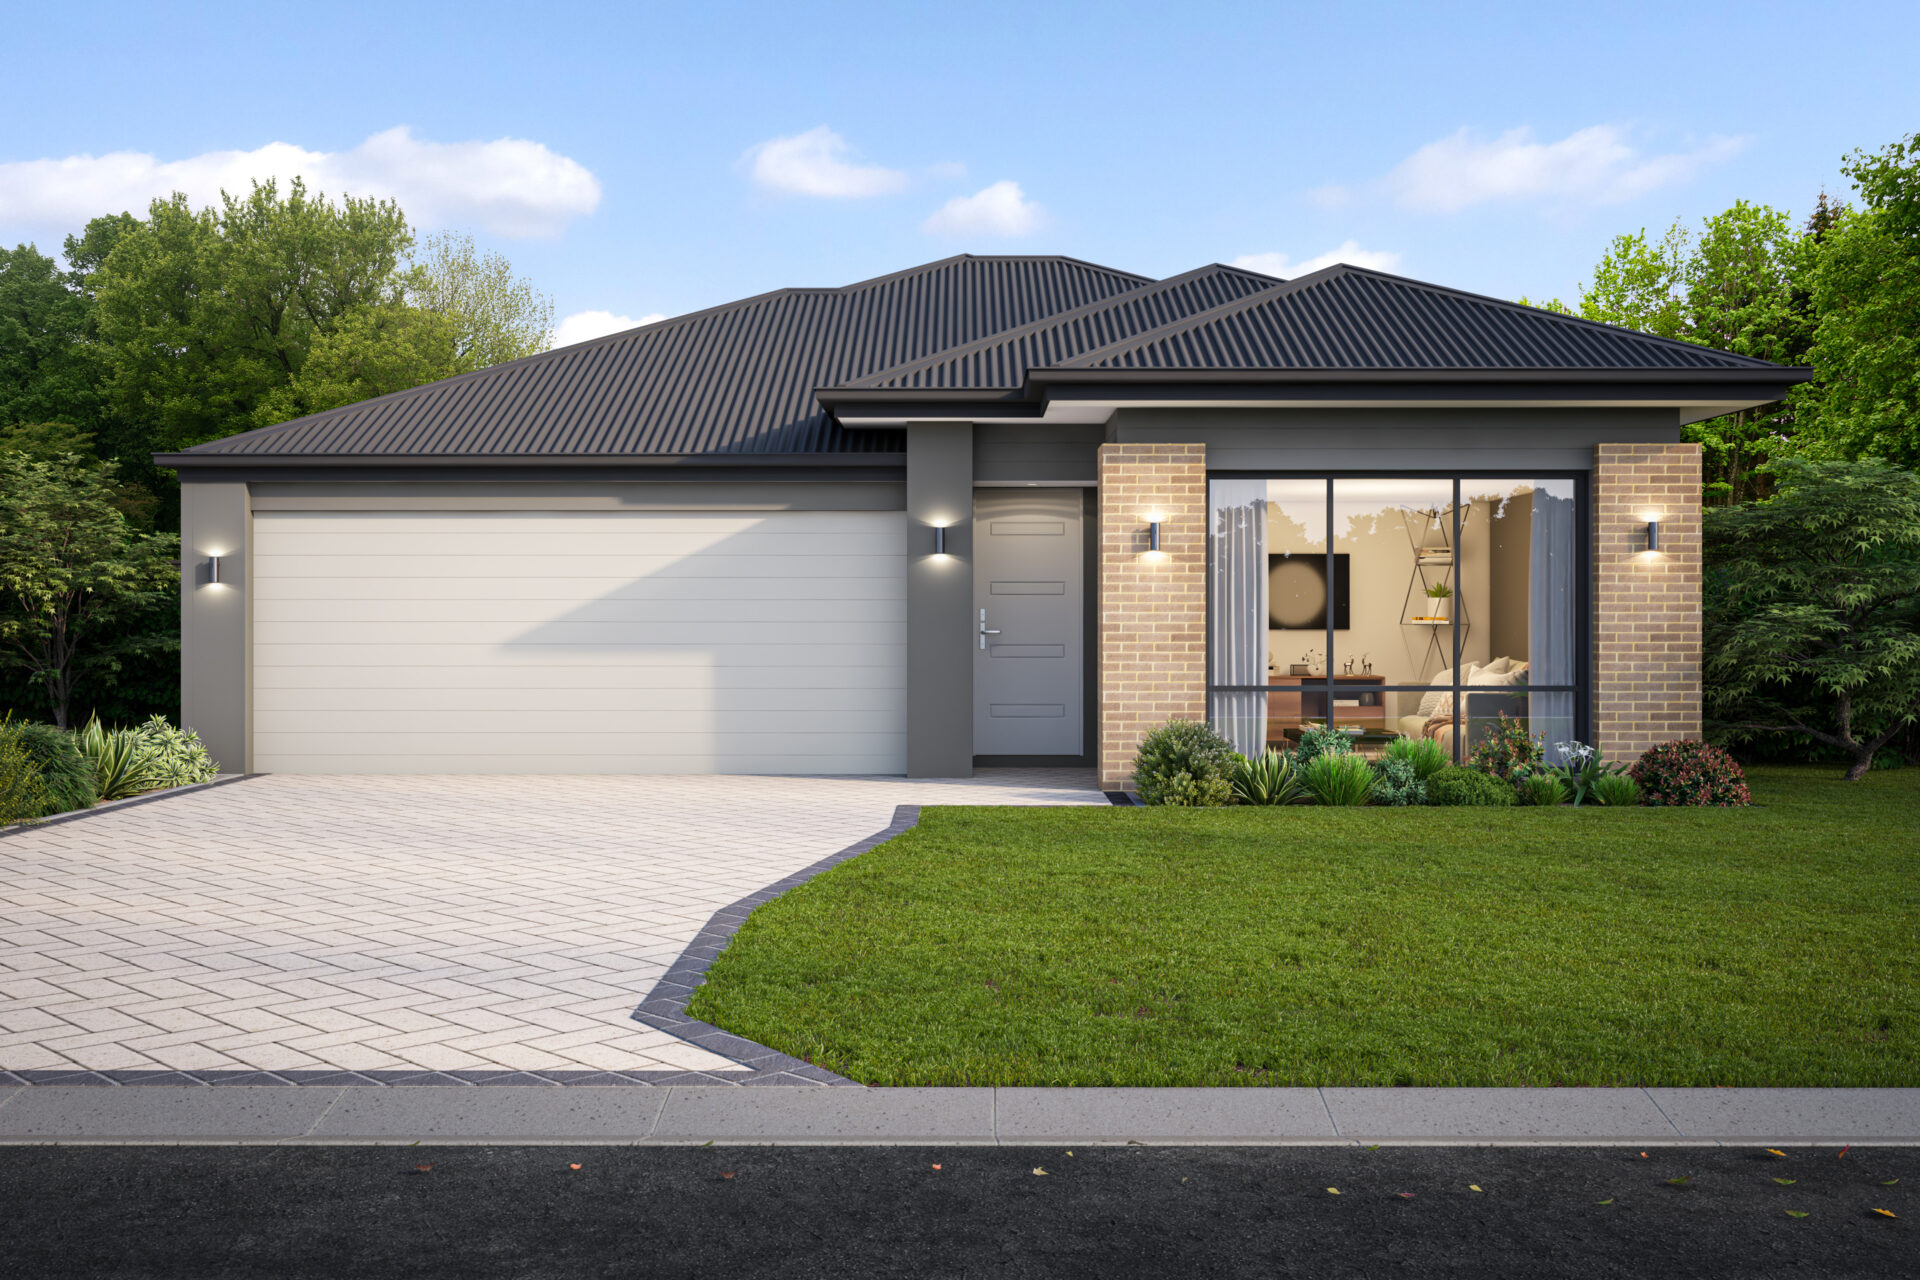
Cardup Lot 151
Cardup, South-East corridor
$690,900
total package
4 bed
2 bath
2 car
155 m²
300 m² lot
- · Titled land, ready to build
- · 15m frontage
- · Turnkey inclusions with the Aspen design
Your equity could be building the next one — or the one after that. A fixed-price build with a defined specification is the same process every time, which is what turns a one-off into a plan.
If you ticked at least two, this pathway is worth understanding.
Money sitting in a home or an underperforming property is doing very little. The question on your mind isn’t “how do I pay less tax” — it’s “what should this be doing instead”.
Owning one property and hoping it appreciates is a start, but it’s not a plan. The plan is putting that equity to work in a way that’s repeatable — building the next one, then the one after that, without each one being harder than the last.
Most people’s second investment property is harder than their first. It doesn’t have to be.
The same guided build process, retold for an investor who already understands property and wants to know exactly what they are buying and why.
Tell us your goals, budget and preferred Perth metro locations — whether you plan to live in the home or hold it as an investment.
A specialist reviews your position and confirms a suitable path forward.
We map borrowing capacity and structure the loan for yield and growth.
Choose from a range of tried-and-tested home designs matched to your land, budget, and goals — whether you will live in it or tenant it.
A preliminary agreement to lock in the design, inclusions, and scope before contract.
A formal fixed-price building contract you sign directly with our trusted builder.
Regular stage updates with a named contact throughout construction, so you always know where things stand.
Handover, tenant-ready or move-in ready, and a refinance opportunity to review.
This is the strongest argument on this page and it has nothing to do with tax. Most people’s second investment property is harder than their first, because the first was bespoke — a hundred decisions, a builder relationship built from scratch, a process that lived in someone’s head. A fixed-price turnkey build with a defined specification is repeatable.
The same steps, the same contract structure, the same specification framework — applied to a different lot. You are not starting from scratch each time. The decisions you made on the first build carry forward.
The same specialists and trusted builder. The relationship and the institutional knowledge are already in place. You are not re-establishing trust with a new set of people each time.
A Preparation of Plan Agreement with a defined specification means the documentation is consistent across builds.
The variable is the land — location, lot size, orientation. Everything else is defined. That is what makes a portfolio a plan rather than a series of one-offs.
A new build puts a dwelling into the market that wasn’t there before, and a household lives in it who may not have been in a position to build it themselves. Buying an established property moves ownership and adds nothing.
For a reader thinking about what they’re leaving behind, this reframes the whole exercise — the portfolio and the contribution are the same act.
A new build sits in a different position under the legislation. Since the 2017 changes to plant and equipment deductions, new and established residential property are treated differently for depreciation purposes. This page explains the difference. It is general information, not advice.
Investors who acquire established residential property generally cannot claim depreciation on the second-hand assets within it. A newly constructed property retains that entitlement alongside capital works deductions.
A depreciation schedule is prepared at handover by a registered quantity surveyor — not by us. We do not determine the depreciation values, and we do not provide tax advice. The schedule is a document you take to your own registered tax agent, who advises on how it applies to your circumstances.
This is general information about how the tax legislation applies to new versus established property. It does not constitute tax advice. newhomes.com.au is not a registered tax agent. You should consult your own registered tax agent before making any investment decision.
Can't find what you're looking for?
Browse our curated home designs and selection of beautiful estates.


This section uses indicative values and interest only repayments. Real figures depend on the specific property, rental income, lending variables, and your tax position.
Mortgage repayments increase when the loan reverts to Principal and Interest. This is general information only and does not constitute financial, tax, or investment advice. You should consult your own registered tax agent or licensed financial adviser before making any investment decision.
Submit your details and a specialist will be in touch within one business day.